Loan EMI Calculator - Calculate Monthly Installments
Calculate fixed monthly loan installments, total interest costs, and month-by-month amortization payoff schedules from your loan terms.
🔒 Financial Data Privacy: All numbers are calculated strictly in your browser with zero server storage.
How to Calculate Your Loan EMI
- Enter the principal amount you want to borrow into the Loan Amount field above.
- Enter the annual interest rate in the Annual Interest Rate box.
- Input your total repayment duration and select either years or months in the Loan Term selector.
- Review your calculated monthly installment, total interest payable, and detailed amortization payoff schedule below.
Parameters Explained
- Loan Term Unit: Switches the repayment period between calendar years and individual months to set the total number of monthly installments.
Key Features
- Fixed monthly installment calculation using the standard reducing-balance banking formula.
- Flexible loan term selection in either calendar years or individual months for exact repayment planning.
- Interactive donut chart showing the exact split between loan principal and total interest.
- Full month-by-month amortization schedule tracking principal paid, interest charges, and remaining balance.
- One-click link sharing and downloadable CSV payment schedules for personal budgeting and accounting records.
- Complete financial privacy that keeps your loan figures and payoff schedules strictly on your own device.
Loan EMI Formula and Payment Breakdown
The Loan EMI Calculator computes fixed monthly installments using the standard reducing-balance loan amortization formula:
EMI = P × [ r(1 + r)^n ] / [ (1 + r)^n - 1 ]
Where P is the principal loan amount, r is the monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments.
For promotional financing or zero-interest loans (0% interest rate), the calculation simplifies to equal straight-line installments:
EMI = P / n
The amortization schedule applies penny-rounding adjustments to the final monthly payment so your closing loan balance reaches exactly $0.00.
Developed and maintained by the ValuNox team, this calculator follows standard consumer banking rules for reducing-balance installment loans.
Financial Disclaimer
Results are for educational and estimation purposes only, not formal financial, tax, or legal advice. Actual monthly installments and borrowing costs depend on your lender's terms, credit profile, and origination fees.
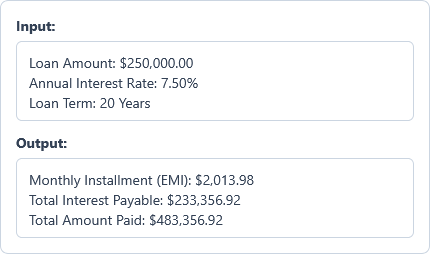
Example Calculation
Example Input
Loan Amount: $250,000.00
Annual Interest Rate: 7.50%
Loan Term: 20 Years
Options used: Loan Term Unit: Years
Example Output
Monthly Installment (EMI): $2,013.98
Total Interest Payable: $233,356.92
Total Amount Paid: $483,356.92
This example shows how fixed monthly installments shift from mostly interest in the early years to mostly principal as the loan balance drops.
Frequently Asked Questions
What does EMI stand for and how does it work?
EMI stands for Equated Monthly Installment. It is a fixed amount you pay to a lender each month until your loan is paid off. Every payment covers both monthly interest on the remaining balance and a portion of the principal.
How does the loan term affect monthly payments and total interest?
A longer loan term lowers your monthly payment, but it increases total interest because interest builds up over more months. A shorter loan term raises your monthly installment, but it pays down the principal faster and cuts your overall interest cost.
Why does the ratio of interest and principal change in each installment?
Interest is charged only on your remaining loan balance, so early payments go mostly toward interest while later payments go mostly toward principal. As your principal balance drops each month, the interest charge gets smaller and more of your fixed payment reduces the debt.
Can you lower total financing costs by paying off principal faster?
Yes, paying down your principal faster lowers your unpaid balance and reduces total interest charges. While a standard EMI schedule assumes fixed monthly payments without prepayments, you can test shorter loan terms above to see how faster repayment cuts your total interest cost.
Does an EMI calculation include loan origination fees and property taxes?
No, the standard EMI formula only covers loan principal and interest. Upfront origination fees, closing costs, insurance, and property taxes must be added separately to estimate your total borrowing cost.
Why does your final monthly installment occasionally differ by a few cents?
Your final payment can differ by a few cents because monthly payments are rounded to two decimal places. Over many months, small rounding differences add up, so the last payment is adjusted by a few pennies to bring the final balance to $0.00.
Do you store or track the loan numbers I enter here?
No, every EMI calculation happens directly on your device. Your loan amount, interest rate, and amortization schedule remain completely private and are never stored or shared online.