Mortgage Calculator - Estimate Monthly Payments
Estimate monthly mortgage principal and interest payments, loan-to-value ratios, total interest costs, and full amortization payoff schedules.
🔒 Financial Data Privacy: All numbers are calculated strictly in your browser with zero server storage.
How to Calculate Your Mortgage Payment
- Enter the total purchase price of the property in the Home Price field above.
- Enter your down payment as a dollar amount or percentage in the Down Payment boxes.
- Enter the fixed annual interest rate from your lender in the Annual Interest Rate box.
- Set the total repayment period in the Loan Term box (typically 15 or 30 years) to view your payment breakdown.
Parameters Explained
- Down Payment ($ / %): Enter either a dollar amount or a percentage; the other box updates automatically to calculate your loan principal.
Key Features
- Fixed monthly principal and interest calculation using standard mortgage amortization formulas.
- Two-way down payment inputs that convert between dollar amounts and home equity percentages.
- Loan-to-Value (LTV) ratio calculation that shows whether Private Mortgage Insurance (PMI) applies at the 80% mark.
- Visual breakdown chart showing the exact share of loan principal, total interest, and down payment.
- Full monthly amortization schedule with final-month cent adjustments so your ending balance reaches $0.00.
- Quick link sharing and CSV export to save or print your full mortgage payment schedule.
- Zero data collection so your home price, down payment, and loan details stay confidential on your device.
Mortgage Payment Formula and Amortization Logic
The Mortgage Calculator determines fixed monthly principal and interest (P&I) payments using the standard residential loan amortization formula:
M = P × [ r(1 + r)^n ] / [ (1 + r)^n - 1 ]
Where M is the monthly mortgage payment, P is the loan principal (Home Price minus Down Payment), r is the monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments (years multiplied by 12).
If the interest rate is 0%, the monthly payment is simply the loan principal divided equally across all months:
M = P / n
This mortgage model rounds each monthly figure to the nearest cent and adjusts the final payment so your remaining balance ends at exactly $0.00.
Developed and maintained by the ValuNox team, this mortgage calculation tool follows US fixed-rate home lending rules and standard international mortgage amortization practices.
Financial Disclaimer
Results are for educational and estimation purposes only, not formal financial, tax, or legal advice. Actual mortgage payments and APR depend on lender rules, your credit score, property taxes, homeowners insurance, private mortgage insurance (PMI), and local escrow fees.
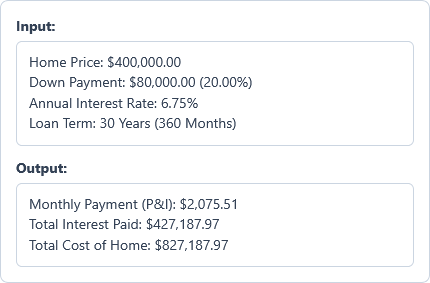
Example Calculation
Example Input
Home Price: $400,000.00
Down Payment: $80,000.00 (20.00%)
Annual Interest Rate: 6.75%
Loan Term: 30 Years (360 Months)
Example Output
Monthly Payment (P&I): $2,075.51
Total Interest Paid: $427,187.97
Total Cost of Home: $827,187.97
This example shows how a 30-year mortgage with 20% down builds up total interest charges that exceed the original amount borrowed.
Frequently Asked Questions
What is included in a monthly mortgage payment?
This calculator estimates your base Principal and Interest (P&I) payment and flags Private Mortgage Insurance (PMI) thresholds based on your down payment. In practice, lenders often add monthly escrow charges for property taxes and homeowners insurance.
What is Loan-to-Value (LTV) and why does 80% matter?
Loan-to-Value (LTV) is the percentage of the home price covered by your mortgage. Putting at least 20% down keeps your LTV at 80% or lower, which usually lets you avoid paying for Private Mortgage Insurance (PMI).
How does a 15-year mortgage compare to a 30-year mortgage?
A 15-year mortgage has higher monthly payments because of the shorter payoff window, but it saves tens of thousands of dollars in total interest compared to a 30-year loan.
How does a higher down payment reduce monthly mortgage costs?
A larger down payment shrinks the amount you borrow, which lowers both your monthly payment and total interest paid. Putting at least 20% down also removes private mortgage insurance (PMI).
What is the difference between a mortgage interest rate and APR?
The interest rate entered above determines your base monthly principal and interest payment. The Annual Percentage Rate (APR) reflects the broader yearly cost of borrowing by adding upfront lender origination fees, discount points, and mortgage insurance.
Does this calculator save my home price or mortgage details?
No, all mortgage calculations happen right on your screen. Your home price, down payment, and amortization schedule stay confidential and are never saved or shared with anyone.